Brazil Junior Oil Sector Enters Third Wave of Onshore M&A
A new wave of micro-operators is sweeping up marginal Brazilian oil fields left behind by larger independent producers, backed by creative retail financing.
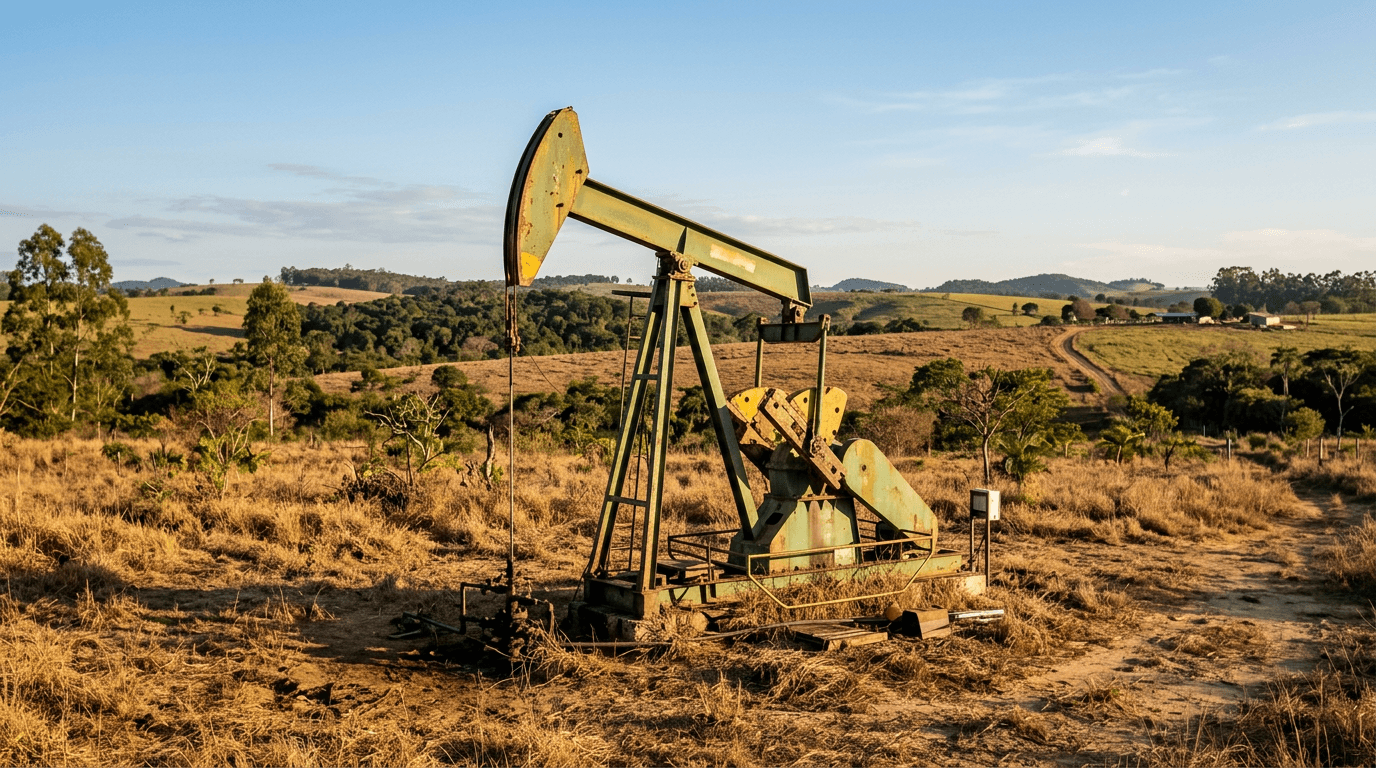
Brazil’s independent oil sector is entering a "third wave" of consolidation as a new tier of micro-operators emerges to sweep up marginal onshore fields. These smaller players are stepping in to acquire assets that have become too small for the country’s established junior majors, utilizing creative financing structures to tap everyday retail investors.
The shift is highlighted by NBS Petróleo e Gás, a startup founded by three former employees of the state-run oil giant Petrobras. The company recently secured regulatory approval from the National Petroleum Agency (ANP) to begin production at two onshore fields, Mosquito and Saíra, in the southeastern state of Espírito Santo. NBS acquired the fields from Origem Energia, an independent producer that has outgrown these smaller, marginal accumulations.
To fund the acquisition, multifamily office L4 Capital bypassed traditional institutional funds. Instead, it raised equity directly from individual retail investors, with ticket sizes ranging from R$ 50,000 to R$ 1.5 million (approximately $9,000 to $270,000 USD), securing a 16% stake in NBS. This retail-backed model mirrors the early, scrappy days of Brazil’s independent oil boom, but at a highly democratized scale.
The evolution represents a distinct third phase for Brazil's oil industry. The first phase was defined by Petrobras's historic monopoly. The second wave arrived when Petrobras divested its mature onshore and shallow-water assets, giving rise to major independent "junior" companies like PRIO, Brava Energia, and PetroReconcavo. Now, as those mid-sized giants scale up and focus on larger targets, micro-operators like NBS are stepping in to run fields that produce as little as 40 barrels per day, proving that ultra-marginal assets can still be highly profitable under lean management.
NBS is already planning its next move. The company has closed the acquisition of another field in Espírito Santo from Mandacaru Energia, financed by a R$ 10 million debenture issue also structured by L4 Capital. As regulatory paths clear and local financing structures mature, this micro-M&A trend is poised to unlock dozens of idle, small-scale wells across Brazil’s traditional onshore basins.
What it touches: While these micro-operators are privately held, the trend highlights the ongoing portfolio optimization of Brazil's larger, publicly traded independent oil producers. Companies like PetroReconcavo (RECV3) and Brava Energia (BRAV3)—formed by the merger of 3R Petroleum and Enauta—are increasingly shedding non-core, lower-yield onshore assets to focus capital on high-margin fields, streamlining their balance sheets for public market investors.